Live Better
How to improve your financial health


(Family Features) Your financial health is just as important as your physical and mental health. Money affects almost every aspect of your life and can be the determining factor in many of your day-to-day decisions.
Being financially healthy isn’t just about how much money you have in the bank. It also encompasses your financial capability and how you feel about money orhow money makes you feel.
Start by doing a self-check to determine your financial health. Look at where your accounts currently stand, including the statuses and balances. The balances in your accounts can be used to calculate your net worth, which is a numerical indicator of your overall financial health from an accounting standpoint.
Also consider your feelings and relationship with money, including the emotions you experience when someone brings up topics involving money. Then determine if you are a saver or spender. Understanding how you feel about your finances and why you have these feelings can help you improve your overall financial health along with these tips from the financial experts at kinly, a financial services company helping Black America build generational wealth.
Set Financial Goals
To improve your financial health, start by setting short-term, mid-term and long-term financial S.M.A.R.T. (specific, measurable, achievable, relevant, time bound) goals. S.M.A.R.T. goal setting can help you be more specific, provide a way to measure your progress, allow you to create a plan to make things more achievable, ensure your goals are in line with other objectives and provide deadlines, so your financial goals don’t get lost in the shuffle of day-to-day life.
Create a Money Plan
A money plan is a guide that details how you want to use your income monthly. This plan should consider the money you want to save and the money you want to spend. As you add your list of expenses, use this opportunity to review where your money is going and if your spending is in line with the financial goals you’ve set. This is also an opportunity to look for ways to reduce or eliminate spending so your money can be used for things that are important to you, like saving for a down payment on a car or home, or purchasing an item from your wish list.
Expand Your Financial Knowledge
Explore ways to become more comfortable with money and take control of your financial future. Your relationship with money and how you feel about it make up your money story. Money stories involve emotions, beliefs and experiences with money from childhood to adulthood. Start by spending 10-20 minutes each day exploring topics around money or personal finances to help build your knowledge base. You can do this by listening to podcasts, reading books, browsing reputable personal finance websites or exploring financial education resources provided by your financial institution.
If you need a more personalized approach to developing a better relationship with your finances, explore working with a financial coach. Your financial coach can work with you on a range of fundamental money management skills. For example, a financial coach can help you overcome financial anxiety or come up with a debt repayment strategy. The coach can help guide, teach, empower and challenge you to grow into a savvy money user.
When determining your financial health, remember personal finance is personal. The financial decisions you make today impact your overall financial health. Determine what financial success looks like for you and incorporate mindfulness, resources and other financially beneficial strategies to help improve your relationship with your finances. Find additional advice and resources to help you manage your money at bekinly.com.
Photos courtesy of Getty Images
SOURCE:
kinly
(Feature Impact) As temperatures cool, now is an ideal time to prepare your home for winter. Taking care of seasonal maintenance before the cold weather arrives can help protect you and your wallet from unexpected and costly repairs.
From clearing gutters to scheduling an HVAC tune-up, tackling a few projects now can help set your home up for a safe and comfortable winter. Consider this your ultimate fall home maintenance checklist from the experts at Carrier.
1. Clean Gutters
Leaves and debris collect quickly in home gutters and downspouts. Make sure they are clear so water can drain properly and away from your home’s foundation. If you wait until after temperatures drop, you run the risk of ice dams and water damage.
2. Inspect Your Outdoor HVAC Equipment
Remove leaves, grass clippings and debris that may have accumulated around your outdoor unit. Maintaining proper clearance can help support airflow and system performance throughout the season.
3. Replace HVAC Filters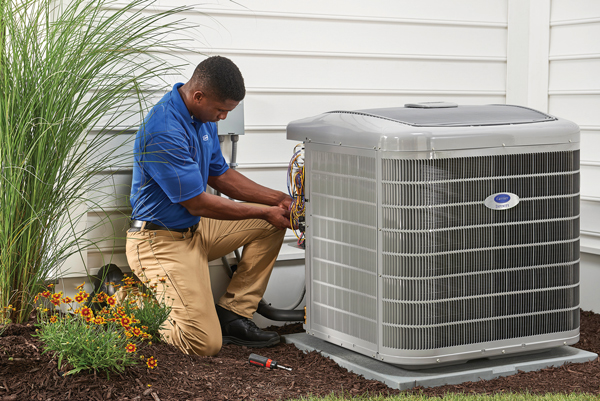
A dirty filter can restrict airflow and force your system to work harder, potentially increasing energy use and reducing comfort. A simple filter check can also help prepare your heating system for increased use. Check your HVAC filter before turning on your heating system and continue inspecting it throughout the winter. To help maintain proper airflow, Carrier typically recommends replacing air filters every 1-3 months.
4. Test Smoke and Carbon Monoxide Detectors
When changing clocks, test your smoke alarms and carbon monoxide detectors. Replace batteries as needed. Working carbon monoxide alarms are especially important as temperatures fall and home heating systems begin running more frequently.
5. Schedule Your HVAC Tune-Up Before Winter Arrives
Don’t wait until the first cold day of the season to find out your heating system isn’t ready for winter. Annual maintenance can help improve efficiency, extend equipment life and identify potential issues before the heating season begins. Experts often recommend having an HVAC professional perform annual furnace maintenance in the fall before heating season begins. Routine maintenance can help keep a system operating in tip-top shape and allow a technician to identify smaller issues before they become costly repairs.
However, if replacement is recommended, the upfront price doesn’t necessarily have to stand between you and a more comfortable home. Consider options from Carrier, which offers flexible financing options through participating dealers. Depending on the financing plan you qualify for and your home’s heating and cooling needs, a new system could cost less than you think. Homeowners can also explore utility rebates on qualifying equipment.
6. Test Your Thermostat
Testing your thermostat early helps ensure your heating system is communicating properly before temperatures drop. Switch to heating mode early to make sure your system responds properly (just don’t forget to turn it back off). Replace batteries, if necessary, and consider whether a smart thermostat could provide additional comfort and control over your home’s heating schedule.
7. Seal Air Leaks Around Doors and Windows
Drafts can make a home feel colder and allow warm air inside your house to escape. Inspect weatherstripping around doors and windows and replace it where needed. Caulk visible gaps to help keep conditioned air inside and improve your family’s comfort.
8. Check Your Home’s Insulation
Finally, look at insulation in areas such as the attic, crawl spaces and basement. Doing so can help keep heated air where it belongs and reduce the workload on your heating system all winter long.
To learn more about preparing your heating or cooling system for the season, exploring financing and rebates or finding a local expert, visit Carrier.com.
SOURCE:

(Feature Impact) Travelers are more likely to trust a travel advisor over AI when the trip becomes complicated, expensive or likely to change. According to new research from ALG Vacations, a leading vacation package provider, 77% of AI users say they are likely to still rely on a human to make final travel decisions when using AI to plan.
The pattern is strongest among younger travelers. Millennials and Gen Z are using travel advisors at the highest rates of any generation, even as they also report higher trust in AI travel recommendations. Younger travelers are using AI and travel advisors for different parts of the same trip.
Are Millennials and Gen Z still using travel advisors?
Yes. Younger travelers are using both AI and travel advisors. In fact, among AI users, the youngest generations use travel advisors most:
- 51% of Millennials have used a travel advisor when booking a vacation
- 51% of Gen Z say the same
- 44% of Baby Boomers report advisor use
- 43% of Gen X report advisor use
The same generations leading on advisor use are also the most trusting of AI travel recommendations. Among AI users, 31% of both Millennials and Gen Z say they completely trust travel recommendations generated by AI, compared with 12% of Baby Boomers. They are using both.
When should you use a travel advisor instead of AI?
Consider using a travel advisor over AI when the stakes are high. AI users turn to travel advisors most often in these scenarios:
- 36% when something goes wrong, such as a canceled flight or a double-booked hotel
- 31% for complex or multi-destination trips
- 27% for group or family travel
- 27% for luxury or high-cost trips
When forced to choose between AI and a travel advisor for final vacation decisions, 44% of AI users pick a travel advisor and 37% pick AI. Among Baby Boomers, the gap widens sharply, with 59% picking a travel advisor and 15% picking AI.
What does a travel advisor bring that AI cannot?
Travel advisors bring human judgment, planning experience and direct support when a trip becomes more complicated. Among AI users, 82% say having access to a human for support when booking a vacation is extremely or very important.
That support matters when travelers are comparing options, booking a higher-cost trip, coordinating multiple people or adjusting plans after a disruption. AI can organize information quickly, but travelers still cite practical concerns about relying on it entirely.
The specific value travel advisors provide includes:
- Relationships with the people who run resorts, hotels and tour operators
- Access to deals and amenities not always available to the public
- Firsthand experience and industry knowledge
- Real-time support when plans change
- Judgment and personalization for complex trip planning
The top concerns AI users have about relying entirely on AI include important details being missed (42%), privacy or security concerns (42%) and having no support if something goes wrong (39%).
Is AI going to replace travel advisors?
No. The data shows AI and travel advisors, still commonly known as travel agents, serving complementary roles rather than competing ones.
AI is used for the research and inspiration stages of travel planning. Travel advisors are used for the booking, more complex decisions and moments when travelers want a person involved.
AI is now part of how people plan trips. Travel advisors are too. The travelers most comfortable using AI are also the ones turning to advisors most often.
To learn more about ALG Vacations and connect with a travel advisor, visit alg.www.vaxvacationaccess.com.
Methodology
ALG Vacations commissioned Atomik Research to conduct an online survey of 1,000 U.S. adults who currently use AI tools. The margin of error is plus or minus 3 percentage points at a 95 percent confidence level. Fieldwork was conducted between April 24 and April 28, 2026.
Atomik Research, part of 4media group, is a creative market research agency.
SOURCE:
(Feature Impact)For most households, buying a new vehicle is one of the largest financial decisions they’ll make. The purchase price is only the beginning, however. Fuel, maintenance, depreciation and insurance all contribute to the total cost of ownership, making affordability a consideration that extends well beyond the showroom.
To help consumers make more informed purchasing decisions, Mercury Insurance recently released its annual rankings of the most affordable new 2026 model year vehicles to insure, identifying the top-performing SUV, truck, sedan and electric or hybrid vehicles in four of today’s most popular categories.
“Consumers naturally compare purchase price, fuel economy, safety ratings and technology features before buying a vehicle,” said Chong Gao, director of research and development for Mercury Insurance. “Insurance is one of the few ownership costs drivers can estimate before making a purchase. Factoring it into the decision gives consumers a more complete picture of what that vehicle is likely to cost over the years they own it.”
While every driver’s premium is unique, this year’s rankings also revealed a broader trend: Practical, mainstream vehicles continue to offer some of the strongest long-term insurance value.
“Vehicles designed for everyday drivers often strike the best balance between safety, repairability and replacement costs,” Gao said. “That’s reflected in this year’s rankings, where familiar models from manufacturers like Hyundai, Chevrolet, Honda, Kia and Volkswagen rose to the top. It reinforces the idea that choosing a practical vehicle can pay dividends well beyond the purchase price.”
A Cost You Can Plan For
Unlike unexpected repairs or fluctuating fuel prices, insurance is a predictable ownership expense consumers can research before purchasing a vehicle.
Comparing insurance costs alongside purchase price, fuel economy, maintenance expenses and expected repair costs can help shoppers better understand the long-term financial commitment of vehicle ownership.
Factors Influencing Insurance Costs
Insurance costs are influenced by many factors, but repair complexity, parts availability, vehicle safety systems and historical claims experience all contribute to how a vehicle is insured. While advanced safety technology can help reduce accidents, vehicles that are easier and less expensive to repair can also help improve long-term affordability. Among the considerations insurers evaluate are:
- Repair and replacement costs
- Historical claims experience
- Vehicle safety features and crash performance
- Theft frequency
- Availability and cost of replacement parts
- Vehicle performance characteristics
The Most Affordable Vehicles to Insure
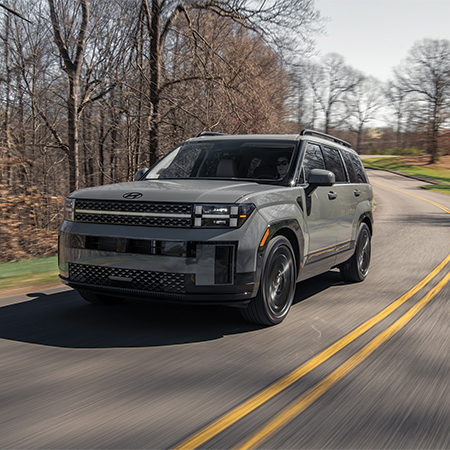
This year’s rankings show practical, mainstream vehicles continue to offer some of the strongest insurance value. The top spot in both the SUV and electric and hybrid categories was claimed by Hyundai while Chevrolet led the truck category and Volkswagen topped the sedan rankings. Rounding out Mercury’s rankings were several familiar nameplates recognized for balancing insurance affordability with everyday value.
SUVs:
- Hyundai Santa Fe
- Chevrolet Blazer
- Honda Pilot
- Kia Sportage
- Honda Passport
Trucks:
- Chevrolet Colorado LT
- Chevrolet Silverado C3500
- Ford Maverick and Ranger
- Hyundai Santa Cruz SE
- Toyota Tundra CrewMax
Sedans and Coupes:
- Volkswagen Golf R
- Acura Integra
- Honda Prelude
- Kia K4
- Mazda3
Electric and Hybrids:
- Hyundai Santa Fe Hybrid
- Chevrolet Blazer EV
- Kia Sportage Hybrid
- Ford Escape Hybrid
- Honda CR-V Hybrid
“The smartest vehicle purchase isn’t always the one with the lowest sticker price,” Gao said. “It’s the one that delivers the best overall value over time. Comparing insurance before buying gives consumers another tool to make a more informed decision.”
Visit MercuryInsurance.com to see the full rankings and request a quote to get a more complete understanding of long-term ownership costs.
Photo courtesy of Hyundai America (Hyundai Santa Fe)
Photo courtesy of Shutterstock (couple using laptop)


-
 NEWS3 years ago
Suspect indicted, jailed in Tia Hutson murder
-
 NEWS4 years ago
2 hurt, 1 jailed after shooting incident north of Nocona
-
 NEWS4 years ago
Wreck takes the life of BHS teen, 16
-
 NEWS3 years ago
SO investigating possible murder/suicide
-
 NEWS3 years ago
Murder unsolved – 1 year later Tia Hutson’s family angry, frustrated with no arrest
-
 Show us something good9 years ago
Country music star children perform in Bowie
-
 100th Birthday4 years ago
Looking back at the 1958 Centennial edition of The Bowie News
-
NEWS3 years ago
Sheriff’s office called out to infant’s death